Total Cost of an Employee in Vietnam (Employer Guide)
Updated 22 October 2026 | A practical guide for employers and foreign-invested companies.
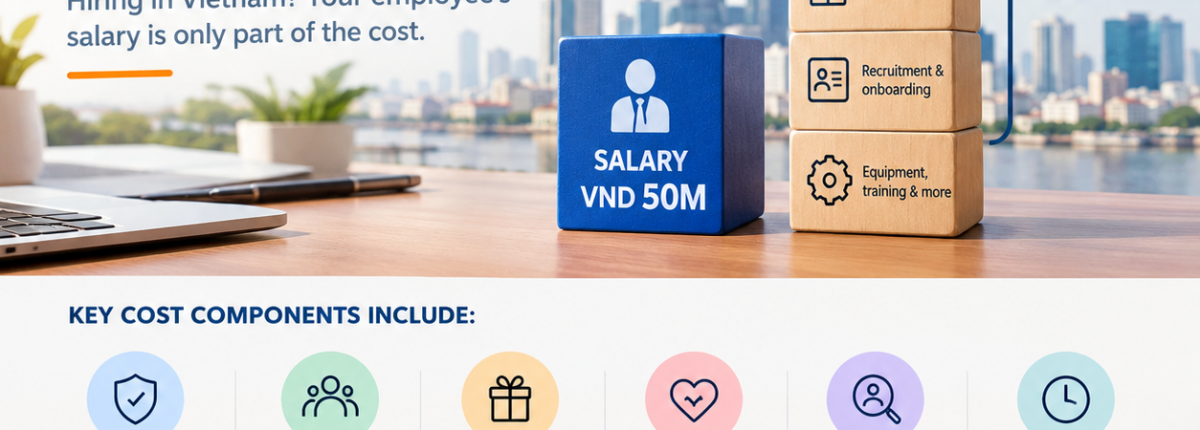
Hiring an employee in Vietnam costs more than the gross salary shown in the employment contract. For employers planning headcount, understanding the employer cost Vietnam businesses incur is essential to building realistic budgets, comparing hiring options and avoiding surprises in payroll.
The cost of an employee in Vietnam can include employer social insurance contribution, health insurance, unemployment insurance, trade union funding, bonuses, benefits, recruitment and onboarding. Under the assumptions in this guide, statutory employer contributions for a typical Vietnamese employee can add approximately 23.5% to the applicable contribution base before bonuses and other benefits. Providing for a 13th-month salary can increase the budgeted monthly cost further.
Rates and ceilings as of 22 October 2026, based on Decree 293/2025/ND-CP, Decree 161/2026/ND-CP, the Law on Social Insurance 2024 and the Law on Trade Unions 2024.
- Gross Salary vs. Total Employment Cost
Gross salary is the contractual salary before deductions for employee-paid insurance contributions and personal income tax (PIT). Total employment cost is broader: it includes gross salary, employer-paid statutory contributions and other expenses associated with employing someone.
For budgeting purposes, divide costs into three categories:
- Direct compensation: Gross salary, bonuses and allowances.
- Statutory costs: Employer insurance contributions and applicable trade union funding.
- Additional expenses: Benefits, recruitment, onboarding, equipment and training.
A consistent method helps HR and Finance compare roles and estimate the full cost of hiring Vietnam businesses should include in annual workforce plans. Keep employee deductions separate from employer costs: employee-paid insurance and PIT are normally withheld from gross pay and are not additional employer expenses, although the employer is responsible for administering applicable payroll obligations.
- Employer Social Insurance Contribution, Health Insurance and Trade Union Funding
For a typical Vietnamese employee subject to all three compulsory insurance schemes, the standard contribution rates are:
Contribution | Employer rate | Employee rate |
Social insurance | 17.5% | 8% |
Health insurance | 3% | 1.5% |
Unemployment insurance | 1% | 1% |
Trade union funding | 2% | – (union members pay separate dues) |
Employer social insurance, health insurance and unemployment insurance contributions total 21.5% of the applicable contribution base. Including trade union funding brings the typical employer total to 23.5%, where all listed contributions apply.
Employers contribute 2% even where no enterprise-level union has been set up. This employer-funded trade union contribution is separate from union dues paid by employees who are members of a trade union. Confirm the applicable funding base and any relevant rules for the employee and business category.
Contribution ceilings
Insurance contributions are not necessarily calculated on the employee’s entire gross salary. From 1 July 2026, the maximum monthly salary used to calculate compulsory social insurance and health insurance contributions is VND 50.6 million, equivalent to 20 times the statutory base salary of VND 2.53 million.
The unemployment insurance ceiling is linked to 20 times the applicable regional minimum wage. In Region I, this is VND 106.2 million per month under the regional minimum wage effective from 1 January 2026.
Once a ceiling is reached, the relevant contribution no longer increases in proportion to gross salary. This can reduce the effective contribution percentage for higher-paid employees. The contribution base may also differ from gross salary because the treatment of salary components and allowances depends on the applicable rules and contractual arrangements.
Regional minimum wages
Under Decree No. 293/2025/ND-CP, effective 1 January 2026, the monthly regional minimum wages are:
Region | Monthly minimum wage |
Region I | VND 5,310,000 |
Region II | VND 4,730,000 |
Region III | VND 4,140,000 |
Region IV | VND 3,700,000 |
Employers should confirm the region applicable to the workplace and use the relevant minimum wage when setting salaries and calculating contribution ceilings.
What about foreign employees?
From 1 July 2025, foreign employees working in Vietnam under a fixed-term employment contract of at least 12 months with an employer in Vietnam generally fall within compulsory social insurance coverage. Exceptions include qualifying intra-company transferees, people who had reached statutory retirement age when signing the contract, and cases where an applicable international treaty provides otherwise. Unemployment insurance does not apply to foreign employees under the standard framework.
Employers should check the employee’s contract, immigration/work status and any relevant international agreement before determining obligations. Health insurance and other requirements should be assessed separately rather than assuming that every rule for Vietnamese employees applies identically to foreign employees. Work permits, document processing and relocation can also create additional costs.
- Allowances and Benefits Offered by FDI Companies
Many foreign-invested companies offer additional benefits to attract and retain talent. Common examples include:
- Meal, transportation and telephone allowances.
- Private medical or accident insurance.
- Annual health examinations.
- Professional training and certification.
- Housing or education allowances for expatriates.
- Team-building activities and Tet gifts.
Budget each benefit as a monthly or annual amount per employee. Annual expenses can be divided by 12 to estimate a monthly provision. Review the personal income tax and compulsory insurance treatment of each benefit separately: favourable PIT treatment does not automatically mean that a payment is excluded from the insurance contribution base.
- Bonuses: 13th-Month Salary, Tet Bonus and Performance Pay
A 13th-month salary is not automatically mandatory for every employee under Vietnamese law. However, it is common practice among many employers, including FDI companies. A Tet bonus is also commonly paid around the Lunar New Year, often in the form of a 13th-month salary or another performance- or policy-based bonus.
Employers should distinguish legal requirements from market practice. A bonus may become binding under an employment contract, collective agreement, company rules or other applicable commitments. Performance bonuses should have clear eligibility criteria, calculation methods and payment conditions.
For budgeting, employers can allocate one-twelfth of the expected annual bonus to each month. For an employee earning VND 50 million per month:
- Annual base salary: VND 600 million.
- Assumed 13th-month salary: VND 50 million.
- Monthly budget provision: approximately VND 4.17 million.
This is a budgeting provision, not an additional payment made every month. Whether a bonus forms part of the insurance contribution base depends on the applicable rules and the nature of the payment.
- Leave, Overtime and Public Holidays
Under the Labour Code 2019, employees working under normal conditions generally receive at least 12 working days of annual leave after meeting the applicable service requirements. Additional leave may apply in certain circumstances.
Vietnam’s current standard annual public-holiday entitlement includes 11 paid days. A draft amendment to add 24 November as a paid public holiday is under National Assembly review; check the latest status when preparing 2027 budgets.
Overtime must comply with applicable consent requirements and working-hour limits. Standard minimum overtime pay rates are generally:
- 150% of the normal hourly wage on a normal working day.
- 200% on a weekly day off.
- 300% on a public holiday or paid day off, excluding the salary payable for that holiday or paid day off.
Additional rules may apply to night work and overtime performed at night. Companies operating shifts, production lines or time-sensitive projects should include overtime, public-holiday staffing and leave coverage in workforce budgets.
- One-Off Recruitment and Employment Costs
Some employment expenses occur only once or periodically but should still be included in hiring budgets.
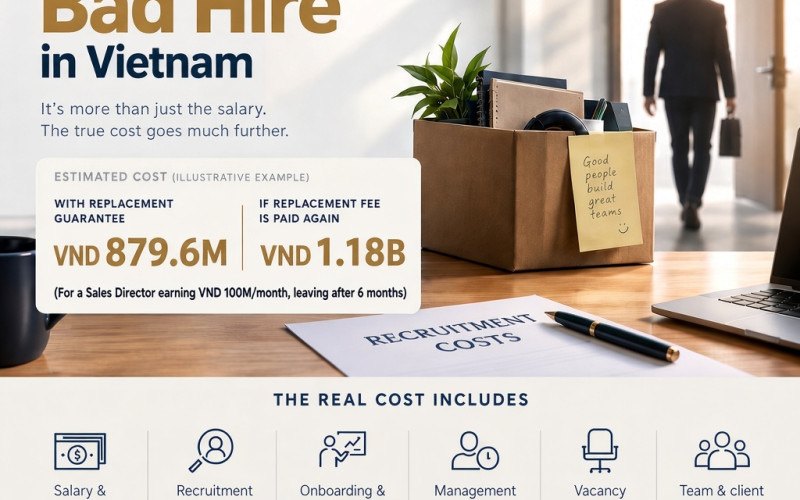
Recruitment: Agency fees, job advertising, internal recruiter time and interview costs. A failed hire can increase these expenses through replacement recruitment and lost productivity. Read our related guide, The Real Cost of a Bad Hire in Vietnam, for a breakdown of direct and hidden costs.
Onboarding and equipment: Laptops, software licences, office equipment, induction and initial training.
Expatriate employment: Work permits, document translation, legalisation and professional advisory fees.
Relocation: Flights, temporary accommodation, housing support and school fees, depending on the expatriate package.
Actual costs vary by role, seniority and company policy. Obtain current quotes before finalising the budget.
- Worked Example: Total Employment Cost at Three Salary Levels
The example below illustrates monthly budgeting for a Vietnamese employee subject to all three insurance schemes. It assumes an insurance salary base equal to gross salary up to the applicable ceilings, a 2% trade union funding contribution on the applicable contribution base, using the assumptions reflected in the table, one additional month of salary annually and no other benefits. Figures are in VND millions per month, rounded to two decimal places.
Cost component | Staff | Manager | Director |
Gross monthly salary | 20.00 | 50.00 | 100.00 |
Social insurance | 3.50 | 8.86 | 8.86 |
Health insurance | 0.60 | 1.52 | 1.52 |
Unemployment insurance | 0.20 | 0.50 | 1.00 |
Trade union funding | 0.40 | 1.00 | 1.01 |
Employer contributions and funding | 4.70 | 11.88 | 12.39 |
Monthly provision for 13th-month salary | 1.67 | 4.17 | 8.33 |
Estimated monthly employment cost | 26.37 | 66.05 | 120.72 |
Cost as a multiple of gross salary | 1.32× | 1.32× | 1.21× |
The example shows why salary alone is not enough to estimate employment cost. Benefits, recruitment, equipment, training, overtime and relocation can increase the total further. Actual payroll calculations should use each employee’s applicable contribution base, eligibility and legal ceilings.
[Download the Total Employment Cost Workbook (Excel)] (Insert the verified public workbook URL before publication.)
Use the workbook to adjust salary assumptions and estimate your workforce budget. Confirm that its rates, ceilings and formulas reflect the rules applicable to your employees.
- Employer Checklist
Before approving a new position or preparing an annual workforce budget:
- Confirm gross salary and the applicable insurance contribution base.
- Verify contribution rates, ceilings and employee eligibility.
- Check the applicable regional minimum wage.
- Include employer insurance contributions and trade union funding, even if no enterprise-level union has been set up.
- Budget for Tet bonuses, a 13th-month salary, allowances and benefits.
- Estimate overtime, leave and public-holiday staffing requirements.
- Add recruitment, onboarding, equipment and expatriate-related costs.
- Review calculations whenever regulations or salary structures change.
- Frequently Asked Questions
What does an employer pay on top of gross salary in Vietnam?
Employers generally pay their share of compulsory insurance contributions and applicable trade union funding. Bonuses, allowances, benefits, recruitment, onboarding and other workforce expenses may add further costs.
Is there a cap on employer insurance contributions?
Yes. From 1 July 2026, the maximum monthly salary used to calculate compulsory social insurance and health insurance is VND 50.6 million (20 times the VND 2.53 million base salary). The unemployment insurance ceiling is 20 times the applicable regional minimum wage; in Region I, it is VND 106.2 million per month. Check the applicable region and employee category before payroll calculation.
Is a 13th-month salary mandatory in Vietnam?
Not automatically for every employee. It may, however, become binding under an employment contract, collective agreement, company rules or other applicable commitments. A 13th-month salary or Tet bonus is common practice but should not be confused with a universal statutory entitlement.
Do foreign employees have the same insurance requirements as Vietnamese employees?
Not necessarily. From 1 July 2025, foreign employees working under a fixed-term contract of at least 12 months generally fall within compulsory social insurance coverage, subject to exceptions such as qualifying intra-company transfers, retirement-age rules and applicable international treaties. Unemployment insurance does not apply to foreign employees under the standard framework. Assess each case individually.
How can a company calculate annual employment cost?
Start with annual gross salary, add employer-paid statutory contributions and applicable trade union funding, then include bonuses, benefits and recurring expenses. Finally, add one-off recruitment, onboarding, equipment and relocation costs. Use current contribution bases and ceilings for each employee.
Planning Your Payroll and Employment Costs in Vietnam?
Accurate employment cost planning helps businesses prepare reliable budgets, manage payroll obligations and make informed hiring decisions.
Our Payroll & PIT Consulting team can support your business with payroll setup, compulsory insurance calculations, personal income tax and workforce cost planning.
Contact our team to discuss your payroll requirements and build a more reliable employment cost budget.
Sources and Further Reading
- Decree No. 293/2025/ND-CP on regional minimum wages, effective 1 January 2026.
- Decree No. 161/2026/ND-CP on the statutory base salary effective 1 July 2026.
- Law on Social Insurance 2024 and applicable implementing regulations.
- Law on Trade Unions 2024 and relevant guidance on trade union funding.
- Labour Code 2019 and applicable implementing regulations on leave, public holidays and overtime.
Disclaimer: This article provides general information for workforce budgeting and does not constitute legal, tax or payroll advice. Employers should verify the applicable rules and individual circumstances before making payroll decisions.
Other Articles